
Honda Financing and Leasing Options in Palo Alto, CA
Author: Anderson Honda team
When considering a Honda, whether it's a fuel-efficient Civic for your daily commute from Palo Alto or a versatile CR-V for family outings to Foothills Park, understanding your financing options is crucial. At Anderson Honda, we know that the choice between financing and leasing can significantly impact your driving experience, especially in our local context of high housing costs and busy roadways like US-101 and I-280. Financing offers long-term ownership benefits, while leasing can provide flexibility and lower monthly payments, aligning with the diverse needs of drivers in Palo Alto and neighboring cities like San Jose and Fremont.
With over a decade of service to our community, Anderson Honda has built a reputation for expertise in maintaining Honda vehicles, ensuring that you receive reliable support throughout your ownership experience. Our local knowledge and trusted experience make us a dependable automotive partner for drivers across Palo Alto and beyond.
Key Takeaways (TL; DR)
- Your Credit Score Matters: A strong credit history is crucial for securing favorable interest rates on loans or leases. This means lower payments over time, which can be significant for Palo Alto drivers juggling high living costs.
- Understanding Financing vs. Leasing: Financing allows you to own your Honda, building equity with each payment, while leasing typically offers lower monthly costs without ownership. This flexibility can suit various lifestyles, whether you're commuting to Stanford Research Park or exploring Foothills Park.
- Lease-End Choices: At the end of your lease, you can choose to buy, lease another Honda, or return the vehicle. This variety helps you adapt to changing needs, whether you're expanding your family or looking for a more efficient model.
- Special Programs Available: Honda often provides incentives for college grads or military members, which can help reduce your overall costs. These offers can be especially beneficial in the tech-savvy and community-oriented environment of Palo Alto.
- Preparation is Key: Before applying for financing, gather essential documents, check your credit, and establish a budget. This proactive approach can streamline your experience, especially in a competitive market.
- Honda's Reliable Financing Options: Many Honda models come with competitive financing rates, making them accessible for families and professionals alike in Palo Alto's high-cost environment.
What Is Automotive Financing?
Automotive financing is the process of borrowing money to purchase a vehicle, often from lenders like Honda Financial Services, banks, or credit unions. When you finance a Honda, you'll agree to a loan amount and pay it back through monthly installments over a set period, known as the loan term. For Palo Alto drivers, this means you can drive a new Honda while managing your budget effectively.
As you make payments, you build equity—this is the portion of the car you own. Once you finish paying off the loan, the bank sends you the car's title, making it officially yours. This is particularly beneficial for those commuting along El Camino Real or enjoying weekend drives to Foothills Park, as it allows you to customize your vehicle and drive without mileage restrictions.
Understanding Honda Financial Services
Honda Financial Services is the official financing partner for Honda, offering a streamlined approach to vehicle financing. This means you can find flexible rates and various programs specifically tailored for Honda buyers right at our dealership.
For those in Palo Alto, you can start the financing process online and apply for pre-approval from the comfort of your home. Offers may vary based on credit history, making it essential to review your options before visiting for a new Honda, whether it's the CR-V or Accord.
With Honda Financial Services, you gain access to exclusive offers that enhance your buying experience, including special rates and incentives that might not be available elsewhere.
What Does It Mean to Lease a Honda?
Leasing a Honda is similar to entering a long-term rental agreement. Instead of paying for the full value of the vehicle, you make monthly payments to use it for a specific period, typically between 24 and 36 months. These payments cover the car's depreciation, which is the difference between its brand-new price and its projected value at the end of the lease, known as the residual value. Additionally, you'll pay a money factor, which is the interest on the lease, along with any applicable fees.
Leasing often results in lower monthly payments compared to financing the same vehicle. This setup is beneficial for those who appreciate having access to the latest features and technology every few years while maintaining a predictable monthly budget for transportation.
When leasing, understanding a few key terms can help you make informed decisions:
- Depreciation: This refers to the decrease in the vehicle's value over time. During the lease, you essentially pay for the amount the car is expected to lose in value.
- Residual Value: This is the estimated worth of the vehicle at the end of the lease period. A higher residual value generally means lower monthly payments.
- Money Factor: Similar to an interest rate, this figure determines the cost of borrowing for your lease. The lower the money factor, the less you pay in interest.
- Typical Terms: Lease agreements usually range from 24 to 36 months, allowing flexibility for those who like to drive new models frequently.
For drivers in Palo Alto, this means you can enjoy the latest Honda technology, such as safety features and infotainment systems, while navigating the area's busy roads or heading to nearby parks. Leasing provides a practical solution for commuting or weekend adventures, especially as you adapt to the local lifestyle.
What Are My Options When My Honda Lease Ends?
As your Honda lease term comes to a close, you have several flexible choices to consider that can suit your lifestyle and needs.
- Buyout Your Leased Honda: Purchase your vehicle at the predetermined residual value stated in your lease agreement.
- Lease or Finance a New Honda: Return your current vehicle and enter a new lease agreement or purchase a new model.
- Return Your Vehicle: Schedule a vehicle inspection and ensure any excess wear or mileage is addressed prior to turn-in.
Understanding the Differences Between Financing and Leasing
When considering a Honda in Palo Alto, it's essential to grasp the fundamental differences between financing and leasing. While financing leads to eventual ownership, leasing allows you to enjoy a vehicle for a specific period without taking ownership.
| Feature | Financing a Honda | Leasing a Honda |
|---|---|---|
| Ownership | Title transfers to you after the final payment is made. | The vehicle remains the property of the leasing company. |
| Monthly Payments | Generally higher, as you're paying for the full value of the vehicle. | Lower, as you're only covering the vehicle's expected depreciation. |
| Upfront Costs | A down payment is often recommended to secure favorable terms. | Typically includes the first payment and acquisition fees. |
| Customization | You can modify the vehicle as desired. | The vehicle must be returned in its original condition. |
| Mileage | No mileage restrictions apply. | Annual mileage limits are enforced, with fees for exceeding them. |
| Wear & Tear | Excess wear may impact resale value. | Fees may apply for any excess wear noted at the end of the lease. |
| End of Term | You have the option to keep, sell, or trade the vehicle. | At lease end, you can return the vehicle, purchase it, or lease another. |
What Factors Determine My Financing or Lease Terms?
Several key factors influence the financing options available to you at Anderson Honda. Understanding these can help you secure the best terms for your new Honda, whether you're eyeing a CR-V or an Accord.
- Credit Score: A higher credit score typically qualifies you for better interest rates, making your payments more manageable.
- Down Payment: A substantial down payment can lower your monthly payments and the overall interest paid throughout the loan.
- Term Length: Choosing a longer term can reduce monthly payments but may increase the total interest paid over time.
- Vehicle Price/Type: The price and type of vehicle, such as a hybrid like the Accord Hybrid, can affect financing deals, especially if there are manufacturer promotions.
- Debt-to-Income Ratio (DTI): Lenders evaluate your DTI to assess your ability to comfortably manage monthly payments without financial strain.
Are There Unique Honda Programs I Can Qualify For?
Honda provides a variety of special programs designed to assist eligible buyers, making it easier for them to own a new vehicle.
- Honda College Graduate Program: A program that offers financial incentives for recent graduates who can provide proof of graduation and employment.
- Honda Military Appreciation Offer: Special savings available for active-duty U.S. military members, veterans, and their spouses.
- Loyalty Benefits: Discounts for current Honda owners looking to purchase or lease a new Honda model.
- Local and Regional Promotions: Offers that vary by dealership or area, changing periodically based on local market conditions.
How to Apply for Honda Financing or a Lease
Getting started with Honda financing is straightforward and can be initiated online, with the option to complete the process at our dealership.
- Get Pre-Qualified: Determine your potential financing terms without impacting your credit score.
- Gather Documents: Prepare your driver's license, proof of income, residency, and insurance details.
- Complete Application: Submit your full application, which includes a hard credit inquiry.
- Review & Sign: Finalize your agreement by confirming the APR, loan term, payment amount, and any additional protections.
Is It Better to Pay Cash or Finance a Car?
Paying cash for a vehicle provides immediate ownership, freeing you from interest payments. However, it can deplete your savings, which might be necessary for emergencies or other investments. For example, if you're eyeing a Honda CR-V and pay in full, you'll own it outright but may lack liquidity for other expenses.
On the flip side, financing allows you to keep your savings intact while distributing the cost over time through monthly payments. This flexibility can be beneficial for drivers in Palo Alto, where housing costs are high. If you choose to finance a new Honda Civic, you might find it easier to manage your budget without sacrificing your savings for unexpected situations.
What Are the Pros and Cons of Each Payment Method?
When considering how to finance your Honda, it's essential to weigh the benefits and drawbacks of each option based on your driving needs and lifestyle.
Pros of Financing a Honda
- You Own It: Once payments are complete, you have full ownership and can sell or trade your Honda whenever you choose.
- No Mileage Penalties: Enjoy unlimited mileage without worrying about overage fees, ideal for daily commutes on El Camino Real.
- Freedom to Personalize: Modify or accessorize your Honda to reflect your style and needs.
- Build Equity: Each payment increases your ownership stake, which could benefit you when selling or trading your vehicle later.
Cons of Financing a Honda
- Higher Monthly Payments: Generally, you'll face higher payments compared to leasing, affecting your monthly budget.
- Maintenance After Warranty: You're responsible for all maintenance and repairs once your warranty period ends, which can be costly.
- Depreciation: As time passes, your vehicle's resale value will decline, impacting your overall investment.
Pros of Leasing a Honda
- Lower Monthly Payments: Leasing typically results in lower payments since you're only covering depreciation costs.
- Newer Vehicles More Often: Benefit from driving the latest Honda models with advanced features every few years.
- Fewer Repair Costs: Leases usually align with warranty periods, meaning you'll often incur minimal repair expenses.
- Easy Turn-In: At the end of your lease, simply return the vehicle without the hassle of selling it.
Cons of Leasing a Honda
- No Ownership: You won't build equity, which means no return on investment when the lease ends.
- Mileage Limits: Leases often come with mileage restrictions, and exceeding these limits can lead to costly per-mile fees.
- Wear and Tear Fees: You may face charges for excessive wear, making it important to maintain the vehicle's condition.
- No Customization: Any modifications must be reverted before returning the vehicle, limiting personalization options.
Tips for Securing the Best Deal on Your Next Honda
Being well-prepared and timing your purchase right can significantly lower your overall costs.
- Check Your Credit First: Review your credit report for errors and address them before applying for financing.
- Shop Around for Rates: Obtain quotes from various lenders, including banks, credit unions, and your dealership.
- Time Your Purchase Wisely: Look for deals during month-end, quarter-end, or model year-end as manufacturers often provide incentives.
- Negotiate the Vehicle Price First: Keep the discussions about financing separate to focus on getting the best price for the vehicle.
- Understand Key Financial Terms: Familiarize yourself with important numbers like cap cost, residual, and money factor for leases, as well as APR and total finance amounts for loans.
Frequently Asked Questions (FAQs)
What credit score do I need for Honda financing?
While lenders consider a variety of credit profiles, higher scores typically lead to better financing offers. For drivers commuting through Palo Alto, showing strong income and a reasonable down payment can enhance your chances of securing favorable terms.
Is it hard to get approved by Honda's captive lender?
Approval depends on individual financial profiles; top-tier rates can be selective. Consistent income and a low debt-to-income ratio are beneficial, especially for professionals working in tech or research sectors around Stanford University.
Can I negotiate the price on a lease?
Yes, the sale price of the vehicle, known as the capitalized cost, is negotiable and impacts your monthly lease payments. Negotiating this effectively can lead to more manageable costs for families heading to Foothills Park or commuting through downtown Palo Alto.
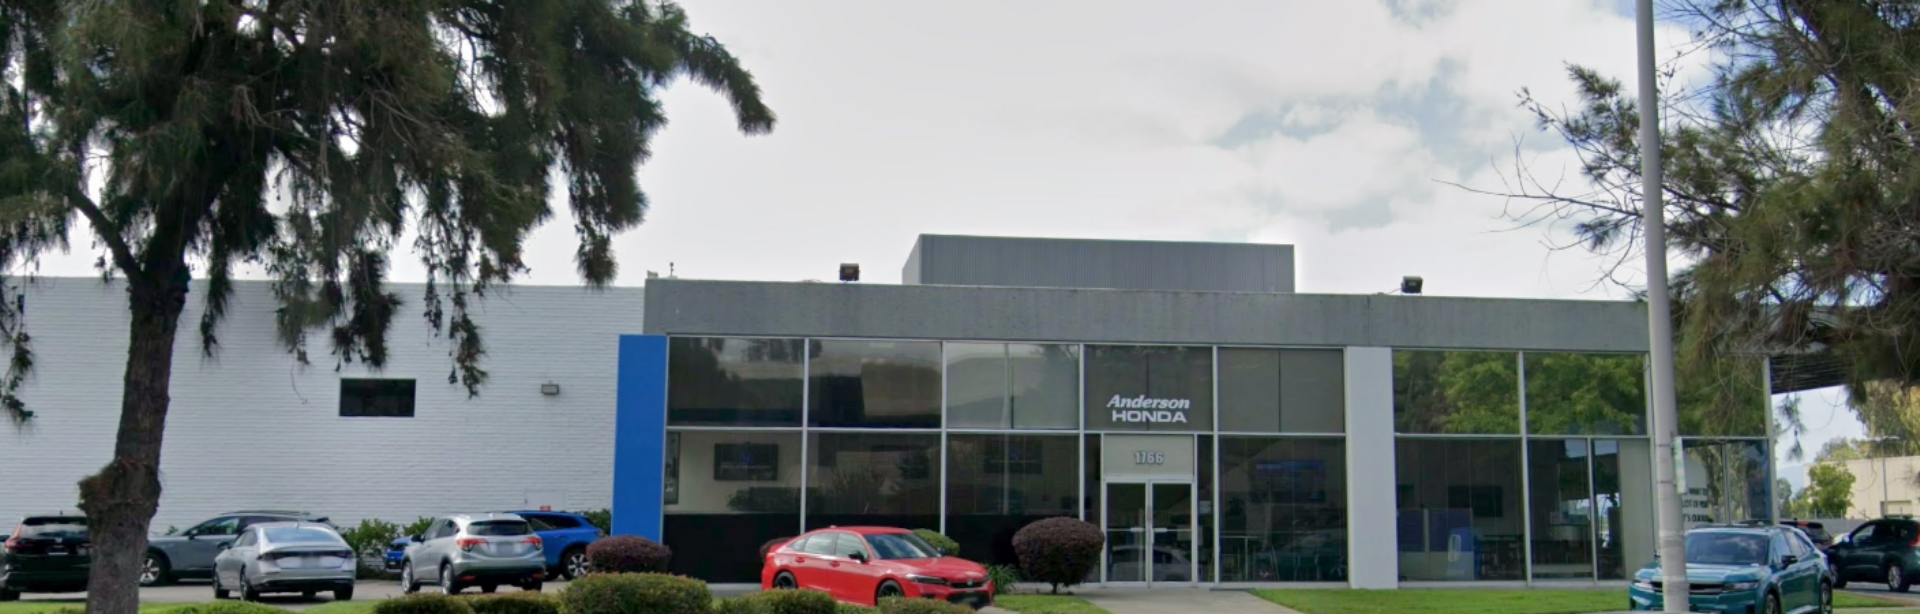
About Anderson Honda
At Anderson Honda, we leverage decades of automotive expertise to provide a transparent and stress-free experience for every driver in Palo Alto and the surrounding Northern California communities. Our long-standing reputation for excellence is built on a commitment to upfront pricing and a customer-first philosophy that has made us a trusted destination for thousands of vehicle buyers annually. We take immense pride in our award-winning service department, where our factory-trained technicians utilize the latest technology to maintain the safety and performance of your vehicle. Beyond the showroom, our team is deeply invested in the local community, striving to give back to the neighborhoods that have supported our growth over the years. Whether you are visiting us from San Jose or Sunnyvale, you can rely on our deep industry knowledge and proven track record to guide you through every mile of your automotive journey.
Related Articles:
The Ultimate Guide to Finding the Best Honda Dealer in Palo Alto, CA
